

November saw another month of continued risk-on behaviour. This saw the MSCI World Index increase by 6.95% and the S&P500 by 5.52%. The risk on behaviour was also welcomed by emerging market countries with the MSCI EM Index gaining 14.84% for the month. (All figures in US Dollar terms).
We feel that most of the returns can be explained by an easing of tensions surrounding inflation fears and lockdowns in China. The CPI print in the US came in slightly lower than expected, but it was enough to instill some confidence in global markets. Although many US companies are still under considerable pressure with staff reductions a general occurrence, there is still some hope that the US could side-step a full-blown recession. In the UK, it’s a whole different story though. Inflation seems to be edging higher still and will probably be going into recession soon (if not already).
China looked to reduce the heavy lockdowns, but it was not to be. This caused major dissatisfaction among the population, causing upheaval throughout the country. Cries for Xi Jinping to step down as leader came through louder and louder until there was not much else to do, but to relax some of the stringent lockdown regulations. This did not mean a complete opening though, as right after the unrests, China logged an all-time record for highest daily COVID-19 cases. But the global equity market saw the relaxation of regulations as a positive and the markets rallied on the idea of trade with China going back to normality in the near future.
Some more news out of the US saw the Democrats fare much better than expected in the US midterm elections. This didn’t have much of an effect on the market, but rather played into the general risk-on nature thereof.
Locally, there was much more on the political front to be concerned about. Although the market still ended the month on a positive, with the MSCI SA Index gaining 19.6% of the month of November, news of president Ramaphosa’s Phala Phala situation seemed to have gotten worse. This is weighing heavily on the sentiment towards the South African market and could have a dramatic effect throughout the month of December. The inflation figure also came in a bit higher than expected, but a reduction in unemployment and increase in GDP growth helped the equity and bond market to finish quite strong.
Prosus and Naspers led the way followed by gold and general mining counters. This is mostly because of optimism towards a China reopening, but we will see how this plays out over the festive season.
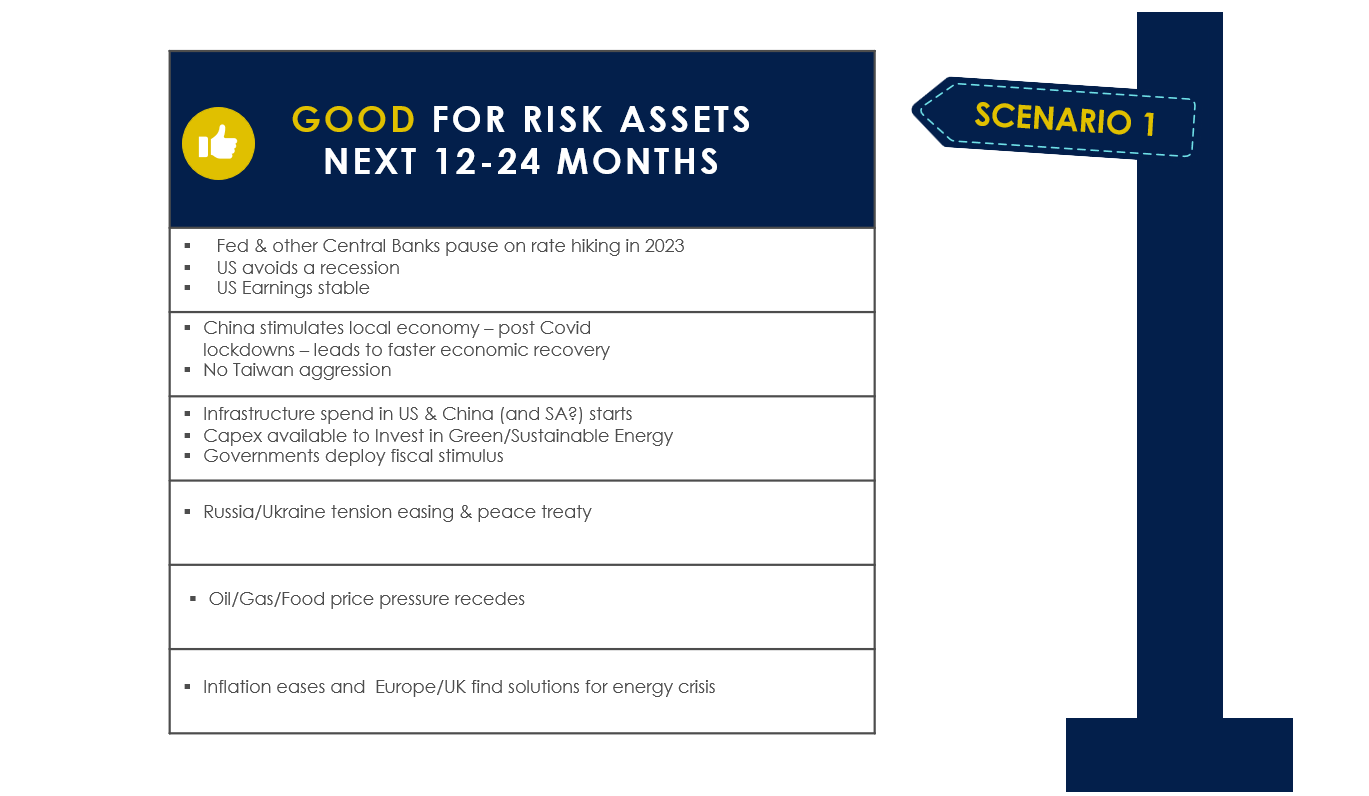
When considering our scenario analysis that we have discussed over the last 6 months, we feel that we are further down the scenario 1 route. From inflation fears to Chinese lockdown restrictions, and all the way to the Russia-Ukraine war, everything looks to be playing out in the right direction.

There are still some meaningful risks, that have not played out yet, and we are cautious to not be too aggressive with our risk allocation. Although inflation is coming down, it’s not going to get to the lows of 2020 anytime soon. Geopolitical tensions are also a major concern as the effects of the war trickle through over the coming northern hemisphere winter period.
But overall, we are pleased with the increase in risk exposure that we started adding back since October. Many of our underlying fund managers (in our model portfolios) also started doing the same and we reaped the benefits. There are still many unknowns and risks that need to account for that are keeping us from going full-out risk. It is, however, clear that there are many opportunities to add to risky assets and that there might be even more in the near future. But for now our portfolios are neutral to underweight global assets and neutral on local risk assets.

Jacques de Kock
Quantitative Analyst & Portfolio Manager
The content of this article is for information purposes only and does not constitute an offer or invitation to any person. The opinions expressed are subject to change and are not to be interpreted as investment advice. You should consult an adviser who will be able to provide appropriate advice that is based on your specific needs and circumstances. The information and opinions contained herein have been compiled or arrived at from sources believed to be reliable and given in good faith, but no representation is made as to their accuracy, completeness or correctness. MitonOptimal South Africa (Pty) Limited is an Authorised Financial Services Provider Licence No. 28160, regulated by the Financial Sector Conduct Authority (FSCA) – Registration No. 2005/032750/07.MitonOptimal Portfolio Management (Pty) Limited is an Authorised Financial Services Provider Licence No. 734, regulated by the FSCA – Registration No. 2000/000717/07.