
At MitonOptimal we take asset allocation (AA) very seriously, taking into consideration both Strategic AA (3-7 years) and Tactical AA within the various asset classes. This quarterly piece provides insight into our short term tactical calls on a 12-month view (reviewed quarterly) and as such may diverge from our long term strategic AA views. We review our strategic AA bi-annually as we believe this is prudent practice, in a world dominated by debt de-leveraging, central bank and political interference.
| Index | Q4-2023 | Q3-2023 |
| FTSE/JSE All Share | 6.92 | -3.48 |
| FTSE/JSE SA Listed Property | 16.37 | -0.97 |
| FTSE/JSE All Bond | 8.11 | -0.33 |
| FTSE/JSE ALB 1-3 Yr | 4.11 | 1.96 |
| Allan Gray Money Market | 2.20 | 2.13 |
| STeFI Composite | 2.09 | 2.07 |
| MSCI World | 8.15 | -3.73 |
| MSCI EM | 4.70 | -3.19 |
| S&P 500 | 8.29 | -3.65 |
| S&P Global REIT | 12.41 | -6.48 |
| GinsGlobal Global Bond Index | 4.58 | -4.84 |
| Bloomberg Commodity | -7.42 | 4.42 |
| USD Money Market | -1.66 | 2.07 |
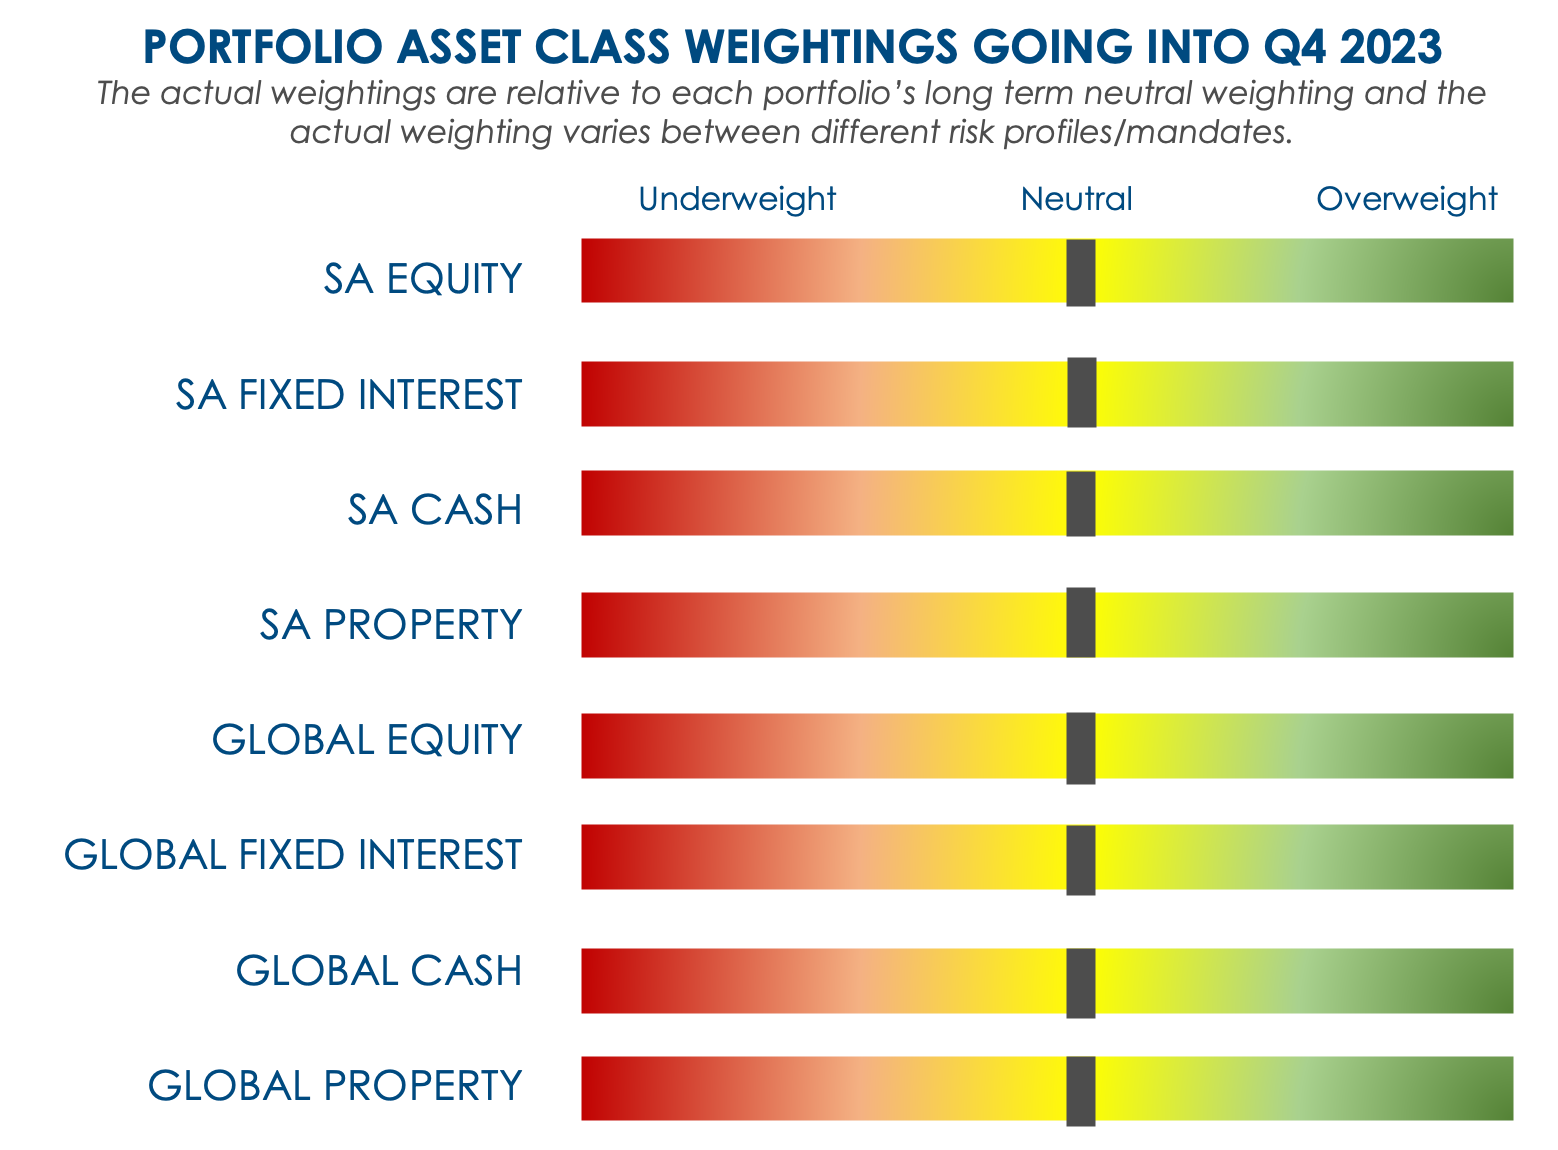
SA EQUITY
UNDERWEIGHT – UNDERPERFORMED
SA Equities didn’t have a bad run in the last quarter of 2023 but continued to underperform relative to other asset classes. Most sectors did well, and with the ZAR appreciating against most other currencies, offshore risk assets only just outperformed. Overall, the JSE All Share Index was up 6.92% for the quarter, bringing the annual return up to 9.25%. Financials (12.27%) led the way in Q4 with resources dropping the overall index by returning -0.04%.
Most of the risk-on behavior was because of the dovish nature of Central Banks.
Most market participants now believe that we should see rate cuts in the US as early as the first half of 2024, or maybe even the first quarter. Most countries are bound to follow, and this could be good news for emerging markets, including South Africa.
We started the quarter in an underweight position but moved to neutral in November. That meant that we could capture most of the uptick in the equity market, but overall, we were underweight. Our underweight allocation to SA Equities had a positive relative influence on our portfolios. We remain neutral SA equities into Q1 of 2024.
SA LISTED PROPERTY
UNDERWEIGHT – OUTPERFORMED
Q4 2023 saw the sector outperform considerably. The SAPY returned 16.37% for the quarter, outperforming all other asset classes. As mentioned, the possibility of early rate cuts would be very positive for property in general and the market reacted in kind.
We moved to neutral in SA Property at the end of November but were overall underweight the asset class. This caused a slight negative relative influence in the portfolios, although our move to neutral captured a big part of the rally.
Pressures pulling down GDP growth and keeping SA Bond yields high are still relevant, but the value in the sector is being unlocked, so we remain neutral going into the first quarter of the year, with an eye on going overweight if we see an opportunity.
SA FIXED INTEREST
OVERWEIGHT – OUTPERFORMED
Like property, SA Bonds had a bit of a rally towards the end of the year. Off the base of high yields and low prices, it was regarded as a positive sign that Central Banks were looking to get dovish. SA Bonds were one of the best performing asset classes for the quarter with the ALBI returning 8.11%, outperforming SA and Global equities in ZAR.
This is encouraging us to look more closely at medium-term Government Bonds as a viable option versus equities and property. With a decent rally and yields coming down, we moved from fixed interest into risk assets by the end of November. This also continues through to the first quarter of 2024.
Fortunately, our overweight on this asset class added to relative portfolio performance in ZAR terms. We remain neutral on bonds going into Q1 but feel that we could move to underweight if bond yields come down and risk assets gain traction.
SA CASH
UNDERWEIGHT – OUTPERFORMED
Our underweight exposure to cash was a positive influence on the performance of our funds, relatively speaking. With the STeFI Composite Index returning 2.09% in a quarter where risk assets did well, and bond yields came down. ZAR strength meant that it outperformed global cash but was still trumped by good returns from risk assets and bonds. We keep the view to be underweight cash in Q1 2024, as we see too many other opportunities to ignore.
GLOBAL EQUITIES
NEUTRAL – OUTPERFORMED
After the AI run of the tech stocks in Q2 last year and the subsequent sell-off in Q3, global equities had a good run in Q4. The world seemed like a better place with inflation dropping and dovish talks from Central Banks.
After our last Strategic Asset Allocation meeting, we preferred global equities over local equities and, although global equities outperformed considerably in USD terms, the strong ZAR in Q4 caused only a slight outperformance. We moved to neutral in the 4th quarter which helped our relative performance with the MSCI ACWI returning 7.78% in ZAR and the MSCI EM Index doing 4.7%, also in ZAR. It was a different story, however, in USD terms as the indices returned 11.03% and 7.86% respectively.
We remain neutral global equities, although we feel that this could change in the next 6-12 months as rate hiking cycles end and the Central Banks and Governments become focused on growth rather than fighting inflation. We also remain biased towards global equities versus local equities, but without diverging much for the market allocation towards developed markets versus emerging markets.
GLOBAL PROPERTY
NEUTRAL – OUTPERFORMED
As with local property, global property had a great quarter returning 15.81% in USD terms (but 12.41% in ZAR). This positive performance was due to the same reasons – value is being unlocked through the possibility of earlier rate cuts.
Last quarter we were on the underweight side of neutral in global property but moved to ‘neutral neutral’ in November after discussions in our SAA meeting.
Our sector allocations also still hold, as we are focused on sectors such as warehousing, storage, data centers and infrastructure. We could be adding more to property if we feel an overweight allocation is warranted and prices revert to the longer-term average.
GLOBAL FIXED INTEREST
NEUTRAL – UNDERPERFORMED
Global bonds performed well in USD terms returning 8.1% (Bloomberg Global Aggregate Index), but the strong ZAR brought the returns down for SA investors to 4.93%. Yields are stabilizing and looked to come down in the last quarter of 2023. It is still unclear if this is a reversal, however, and we remain on our neutral stance. We believe the next few months will be telling and show the direction the FED and other Central Banks will take. But if inflation continues downward (which is our base case) and stimulating growth becomes a factor, we could see yields coming down which will make this an interesting space to be in.
GLOBAL CASH
NEUTRAL – UNDERPERFORMED
As with local cash exposure, the global cash allocation is used as either a risk mitigator or as a place holder for future deployment into risk opportunities. We moved to neutral exposure in Q3 / Q4 with a lack of opportunities being the main reason. This has proven to be a good move as a strong ZAR caused global cash to be the worst performing asset class returning -1.66% in ZAR terms.
We feel confident in maintaining an overweight exposure into Q4, using Global Cash as a risk mitigation tool when and where appropriate.
We are seeing more opportunities now heading into 2024, so there might be a move to underweight if the trend persists.
There are still many risks that we fear could play out over the medium term and we are therefore cautious on adding too many risk assets just yet, but our base case scenario will have us moving overweight risk assets when Governments and Central Banks start to prioritize growth over inflation targeting.
All data sourced from Morningstar
DOWNLOAD: QUARTERLY MARKET INSIGHTS: Q4 2023

Jacques de Kock
Quantitative Analyst & Portfolio Manager
The content of this article is for information purposes only and does not constitute an offer or invitation to any person. The opinions expressed are subject to change and are not to be interpreted as investment advice. You should consult an adviser who will be able to provide appropriate advice that is based on your specific needs and circumstances. The information and opinions contained herein have been compiled or arrived at from sources believed to be reliable and given in good faith, but no representation is made as to their accuracy, completeness or correctness. MitonOptimal South Africa (Pty) Limited is an Authorised Financial Services Provider Licence No. 28160, regulated by the Financial Sector Conduct Authority (FSCA) – Registration No. 2005/032750/07.MitonOptimal Portfolio Management (Pty) Limited is an Authorised Financial Services Provider Licence No. 734, regulated by the FSCA – Registration No. 2000/000717/07.